The Wire Was Bigger Than the Down Payment: St. Louis Closing Costs, and Missouri's $0 Transfer Tax
Revised October 29, 2026
What are typical closing costs in Missouri?
Plan on 2% to 5% of the purchase price, the range Freddie Mac tells buyers to prepare for: if you buy a $300,000 St. Louis home, that is roughly $6,000 to $15,000, on top of the down payment. Missouri adds no transfer tax, because its constitution bars any new tax on selling real estate, so the government line is mostly recording fees. In the City of St. Louis, a standard deed is $25 for the first page.
Keep reading ↓The wire-transfer form is one page, and your hand still shakes on it. The bank counter is cold under your wrist. The teller reads the title company’s account number back to you twice, slowly, and you check every digit against the email, because everyone has told you about wire fraud. Then she reads the amount, and it is not the down payment you memorized to the dollar. It is bigger. That gap is closing costs, and almost nobody rehearses it.
Here is the part that makes St. Louis different from almost anywhere else in the country: which side of the river your house sits on changes the bill. Missouri’s constitution prevents the state, counties and other political subdivisions from imposing any new tax on the sale or transfer of homes or any other real estate. Cross into Illinois and the state charges 50 cents for each $500 of value, and a county can add 25 cents more. If you buy a $300,000 house in the Metro East, that is about $450 in transfer stamps at 75 cents per $500. On the same price in Missouri, it is zero.
Same metro. Same commute. Different bill. Say that to the friend shopping both sides of the bridge.
And inside the city limits, a blank strip of paper has a price. The City Recorder lists a standard deed at $25 for the first page and a nonstandard deed at $50, and what makes a deed standard is mostly a 3-inch blank top margin on page one. Ask your title company whether every document you record is standard format. Below: what the bill holds, how big it gets, what you can move, and how to read your two federal forms side by side.
What are typical closing costs in Missouri?
Plan on 2% to 5% of the purchase price, the range Freddie Mac tells buyers to prepare for: if you buy a $300,000 St. Louis home, that is roughly $6,000 to $15,000, on top of the down payment. Missouri adds no transfer tax, because its constitution bars any new tax on selling real estate, so the government line is mostly recording fees. In the City of St. Louis, a standard deed is $25 for the first page.
The number feels worse than it is, and here is why. Part of that 2% to 5% is not a fee at all. Prepaid interest, the first year of homeowners insurance and the opening escrow deposit are your own money moving forward in time; you were going to owe taxes and insurance anyway. Ask your lender to split the total into money spent and money prepaid, and watch your shoulders come down an inch.
Freddie Mac’s own closing cost explainer says the amount varies greatly depending on your location and the price of your home, which is exactly why a range is a sanity check and your Loan Estimate is the real number. The CFPB’s guide to sizing your down payment is the place to plan both piles of cash together.
The City deed that costs double
This one is pure St. Louis, and almost nobody outside a title office knows it. The City of St. Louis Recorder of Deeds lists a standard deed at $25 for the first page plus $5 for each additional page. A nonstandard deed costs $50 for the first page. What makes a deed standard is mostly formatting: the City’s land records requirements call for a 3-inch blank top margin on the first page, void of any text, writing or graphic. A stamp, a scribble or a logo in that strip, and the fee doubles.
Your title company prepares the documents, so this is usually their problem, not yours. But it is a fair question at the closing table: are all of our documents standard? The City Recorder’s land records office is in City Hall, Room 126, at 1200 Market St., and the line is (314) 622-3260. The land records page carries the current fee list; check it, because fees change.
The river line: $0 on one side, stamps on the other
Drive east over the Poplar Street Bridge, the river brown and wide under the deck, and the rules for your closing bill change before you reach the other bank. Read the Missouri rule in its own words. Article X, Section 25 of the Missouri Constitution says the state, counties and other political subdivisions are prevented from imposing any new tax, including a sales tax, on the sale or transfer of homes or any other real estate. So on a purchase in the city, St. Louis County or Jefferson County, the taxes-and-government-fees section of your disclosure holds recording charges and little else.
Illinois works the other way. The Illinois Department of Revenue explains that the state tax is imposed on the privilege of transferring a beneficial interest in real property located in Illinois. The statute sets the state rate at 50 cents for each $500 of value, and the Counties Code lets a county add 25 cents for each $500. Every Illinois sale is reported on Form PTAX-203, the Illinois Real Estate Transfer Declaration, and the IDOR instructions for that form are worth a skim before you budget. Then call city hall in the town where the house sits and ask whether it adds a stamp of its own, before closing week rather than during it.
Who pays those stamps is a line in your contract, not something to assume. Read it with your pen in hand before you sign.
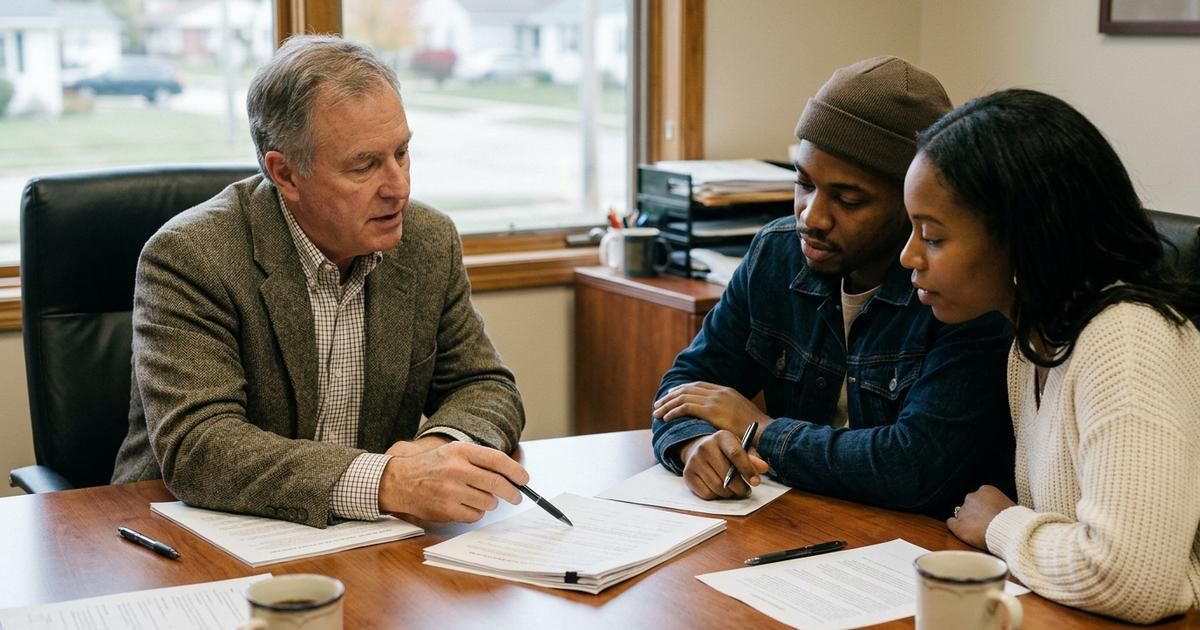
The line items, one section at a time
The Loan Estimate breaks costs into lettered sections, and once you learn them you can read any lender’s paperwork. The paper smells like toner and the font is small, so take it slow.
- Section A, origination charges. The lender’s own fees, plus any discount points you chose. The cleanest number to compare between two lenders.
- Section B, services you cannot shop for. The appraisal, the credit report and similar items the lender picks.
- Section C, services you can shop for. Title work, settlement fees and the lender’s title policy. If you are allowed to shop, the lender has to give you a written list of providers and tell you that you may choose a different one.
- Section E, taxes and government fees. Recording, plus transfer tax in Illinois.
- Sections F and G, prepaids and escrow. Your own money, collected early.
- Section H, other. Often the owner’s title policy, HOA documents and any attorney fee.
The bill on each riverbank
What's the typical closing cost on a $300,000 house?
Budget 2% to 5% of the price; if you buy a $300,000 home, that is about $6,000 to $15,000. On the Missouri side the transfer tax is $0 and a standard City deed records for $25 for the first page. On the Illinois side, state and county stamps at 75 cents per $500 add about $450 if you buy that same $300,000 house, and the town may add its own.
Section C is where the quiet savings live. Most buyers take the first settlement company on the list without a second look, and never ask what a second quote would say. A phone call costs you nothing but a few minutes on a lunch break.
What moves your number most is not the state line, though. It is points, the size of the escrow deposit, and the day of the month you close, since prepaid interest runs from closing to the end of the month. Ask your lender which date in the month makes your cash to close smallest.
Who pays closing costs in MO?
Your purchase contract decides it. The buyer usually carries the costs tied to the loan and their own due diligence, and the seller carries the costs of handing over a clear title, but every line can be negotiated. A seller credit toward your costs is a common ask, and sometimes an easier one for a seller to say yes to than a lower price. Your loan program caps how big that credit can be, so ask your lender for your exact limit before you write the offer.
Short on cash for the table? Some help covers closing costs, not just the down payment: see the St. Louis assistance programs.
Reading your Loan Estimate against your Closing Disclosure
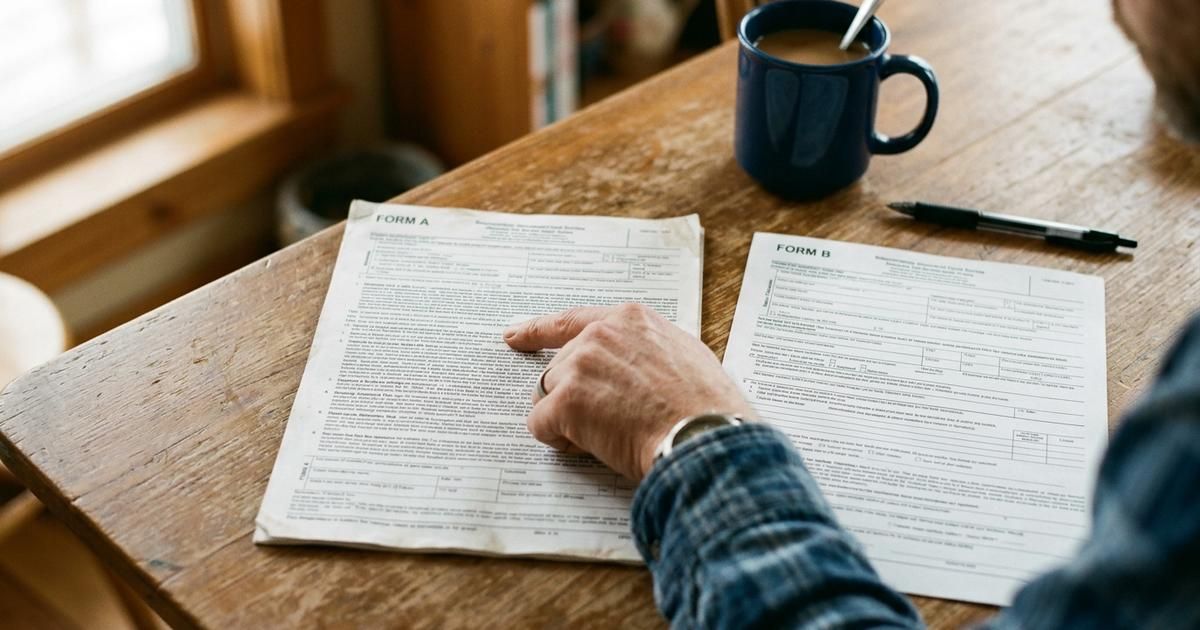
This is the part with federal teeth. Federal rules say you must receive your final loan disclosures no later than three business days before consummation; the CFPB’s Closing Disclosure guide walks through the form. Use those days. Lay the two forms side by side on the kitchen table, section letter against section letter, and circle every line that moved.
Some lines may move and some may not. Charges for certain third-party services, such as recording fees, can rise only so far: the rule lets them grow by no more than 10 percent in total. The CFPB explains which final costs can increase from the estimate. If a lender goes over a limit, it can cure it by refunding the excess to you no later than 60 days after consummation, which is why a buyer who never compares the forms may never learn a check was owed.
For more on fees, read the CFPB on junk fees in housing costs. Question anything you cannot name.
What to ask before you sign anything
- What is the total in Section A, and what is each line inside it?
- How much of my cash to close is fees, and how much is prepaids and escrow?
- What is the largest seller credit my loan allows?
- Can you quote this with a lender credit, with no points, and with one point, with the break-even in months?
- Where is your written list of settlement providers?
- If the house is in Illinois, which transfer stamps apply, and who is buying each one?
- Are all of the documents we are recording standard format?
- Which day of the month would make my cash to close smallest?
Get the answers in writing, and ask two or three St. Louis mortgage lenders the identical questions so the answers line up side by side.
Bring this list to the table, not just your checkbook. If you are earlier in the process, start with the first-time homebuyer’s guide to St. Louis, then read what St. Louis home inspections miss before you waive anything to win a house.
If you’re the title agent, closing attorney or loan officer buyers should be calling, they are comparing names right now, usually late at night with the Loan Estimate open. A Gold listing on St Louis Near Me Directory puts you in front of more customers at that exact moment. See the Gold plan.
Closing costs are the one-time bill. These cover what comes next:
- Escrow and PMI, and how to drop PMI
- What a mortgage rate is
- Choosing a St. Louis real estate agent
- Where to eat in Ballwin, for the dinner after you get the keys
- List your business on St Louis Near Me Directory
Frequently asked questions
What are typical closing costs on a $250,000 house?
If you buy a $250,000 house, the 2% to 5% range Freddie Mac uses works out to about $5,000 to $12,500. In Missouri there is no transfer tax on top. If you buy that $250,000 house in Illinois, state and county stamps at 75 cents per $500 add about $375.
How much would the closing cost be on a $300,000 home?
If you buy a $300,000 home, the 2% to 5% range Freddie Mac gives buyers works out to roughly $6,000 to $15,000. If that $300,000 home is in Illinois, add about $450 in state and county transfer stamps at 75 cents per $500, plus any stamp the town charges. Missouri charges no transfer tax, so a Missouri buyer at the same price skips that line entirely. Your Loan Estimate is the real number; the range is the sanity check.
What would closing cost be on a $400,000 house?
If you buy a $400,000 house, 2% to 5% works out to about $8,000 to $20,000. The high end usually means points, a large escrow deposit or an early-month closing. If that $400,000 house is in Illinois, state and county stamps at 75 cents per $500 add about $600.
How much are closing costs on a $500,000 property?
If you buy a $500,000 property, the 2% to 5% range works out to about $10,000 to $25,000. If it is in Illinois, state and county stamps at 75 cents per $500 add about $750 on that $500,000 price, and a town may add its own; in Missouri, the transfer tax line is $0. At this price, points and the escrow deposit swing the total more than anything else, so ask for the loan quoted more than one way.
Can a seller refuse to pay closing costs?
Yes. A request for seller-paid costs is a term in your offer, and the seller can accept it, counter it or turn it down. If you need the credit to close, put it in your first offer rather than asking after the inspection.
The wire form will still make your hand shake. But you will know what is inside the number: a lender’s pricing, a recorder’s fee list, a state line that decides whether there is a transfer tax at all, and a stack of your own money collected a little early. Three business days is how long the law gives you to look. Take every one of them.
Written by a dedicated team of St. Louis locals who live, work, and play right here in the St. Louis metro. Founder Lane Forman and team are committed to building the region’s most trusted directory by verifying listings and connecting local businesses with loyal customers across Missouri and Illinois.